The long-term case for apartments remains compelling. But for many deals, the case for buying does not make sense in the near-term.
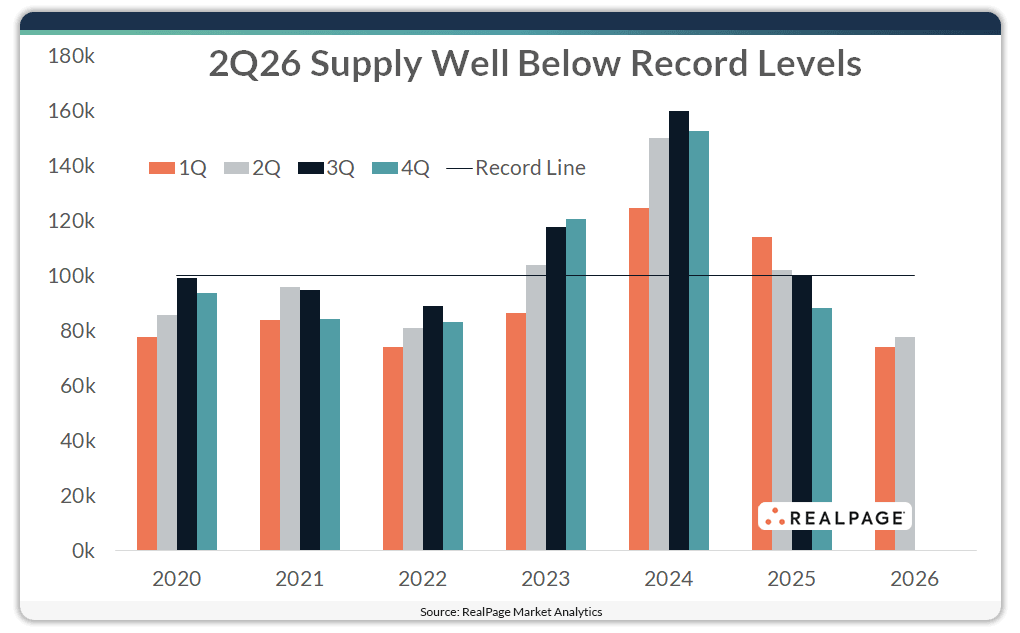
A market can have renters, occupied apartments, and real long-term housing needs, while many acquisitions fail to make sense because the debt is too expensive, the purchase price is too high, rents are testing the limits of affordability, or the submarket is still working through excess supply.
For much of the 2010s, apartment investors benefited from unusually strong tailwinds. Debt was cheap, values were rising, demographics were favorable, supply was limited, and rent growth was broad. Many deals worked because the broader market was conducive.
Today’s market is different. The apartment business still works, but the “easy” apartment trade of the previous cycle is not a reality in this cycle.
Successful investing now requires greater discipline around the fundamentals. What you pay, how you finance it, what your renter can afford, and how much competing supply the market must absorb.
When Debt Costs More, the Purchase Price Has To Work Harder
When the 10-year Treasury hovers high, roughly at the 5% level as of October 2026, it changes the comparison for real estate deals. If investors can earn around 5% in Treasuries with less work, less debt, and more liquidity, then an apartment acquisition has to offer a return that justifies the additional risk.
Our CIO Bill Stoll made this point. “If agency debt is difficult to secure below 6%, while many apartment assets are still priced around 5.25% to 5.50% cap rates [the property’s income yield before debt], the math remains thin. Basically, the debt can cost more than the property’s current yield, and that creates pressure on cash flow and leaves less room for error.”
Those deals simply do not make sense if the purchase price and debt terms do not work, even when the property is in a good location, has a strong investment story, and benefits from long-term renter demand. When debt is expensive, the purchase price has to carry more of the investment case. A buyer needs stronger current income, a better basis [the price paid relative to income and value], better debt, or some combination of the three.
Long-Term Apartment Demand Remains Relevant, But Needs To Be Measured Correctly
Multifamily demand is the number of households that need rental housing, can afford the rent, and choose an apartment over buying a home or renting somewhere else. That definition is more useful than simply saying “people need housing” because it focuses the investor on the actual renter. Who is the renter? What can they afford? How much of their income already goes to housing? Are they choosing this property because it fits their life, or because a concession made it temporarily cheaper than the property next door?
The long-term demand case is still supported by the cost of homeownership. Realtor.com reported that renting a starter home was less expensive than buying one in all 50 of the largest U.S. metros in July 2026, with buying costing an average of $858 more per month than renting. CBRE’s 2026 outlook points to a similar gap, citing a 105% monthly premium to buy versus rent and an estimated 3.4 million single-family home shortage.
Demand has to be understood with care because many renters are already stretched. Harvard’s Joint Center for Housing Studies shows the pressure on households as well. Home prices have increased 54% nationally since 2020, and 22.7 million renter households, or 49% of renters, were cost-burdened in 2024.
This is where the investor and the renter meet. If the investor pays too much for the property, the business plan often depends on pushing rents higher to fix the math. If the investor pays a fair price, uses responsible debt, and operates the property well, the investment has a better chance of producing a fair return without asking the renter to carry the cost of an overpriced deal.
The strongest long-term demand is not just for any apartment at any rent. It is for well-located rental housing where the rent is still realistic for the people living and working in that market.
The New Cycle Has Narrowed the Criteria for a Viable Deal
The apartment market does not need the last cycle to return in order to become investor friendly again.
The last cycle helped buyers in ways that are hard to repeat, when capital was cheaper, values were rising, rents were growing quickly, and many exits benefited from lower cap rates.
The next viable deal will have to earn its return the old-fashioned way.
With a purchase price that makes sense, debt that does not overburden the property, enough time for income to compound, and operations that quietly improve the asset over the hold period.
This cycle will continue to push multifamily back toward a more traditional model, where current income and operations matter more than cheap debt and quick exits.
Adjusting to this reality is challenging, but necessary. A deal has to be weighed with the right measure at purchase, because what is ignored at the beginning eventually has to be carried by the investment plan. The easiest loss to recover from is the deal you had the patience not to purchase.
To learn more about how Steadfast is approaching today’s market, read our Investment Thesis.
Disclaimer: The information provided in this article is for informational and educational purposes only. It is not intended to serve as investment, tax, or legal advice, nor should it be interpreted as an offer to buy or sell any security. Private real estate investments carry significant risks, including the potential loss of principal, and are intended for accredited investors who understand and can bear those risks. Any discussion of tax treatment relates solely to the property-level structure and does not reflect or predict individual investor outcomes. Tax implications vary based on each investor’s circumstances, and readers should consult their own financial, legal, and tax advisors before making any investment decision.